Medicare Advantage vs Medigap in 2026: The Real Differences That Affect Your Wallet and Doctors
Every year during open enrollment, millions of people turning 65 (or already on Medicare) face the same confusing choice: Medicare Advantage or Medigap (Medicare Supplement)?
Here’s a straightforward breakdown without the marketing fluff.
Original Medicare (Parts A and B) covers hospital and medical services but leaves gaps—deductibles, coinsurance, and no annual out-of-pocket maximum. That’s where the two main options come in.
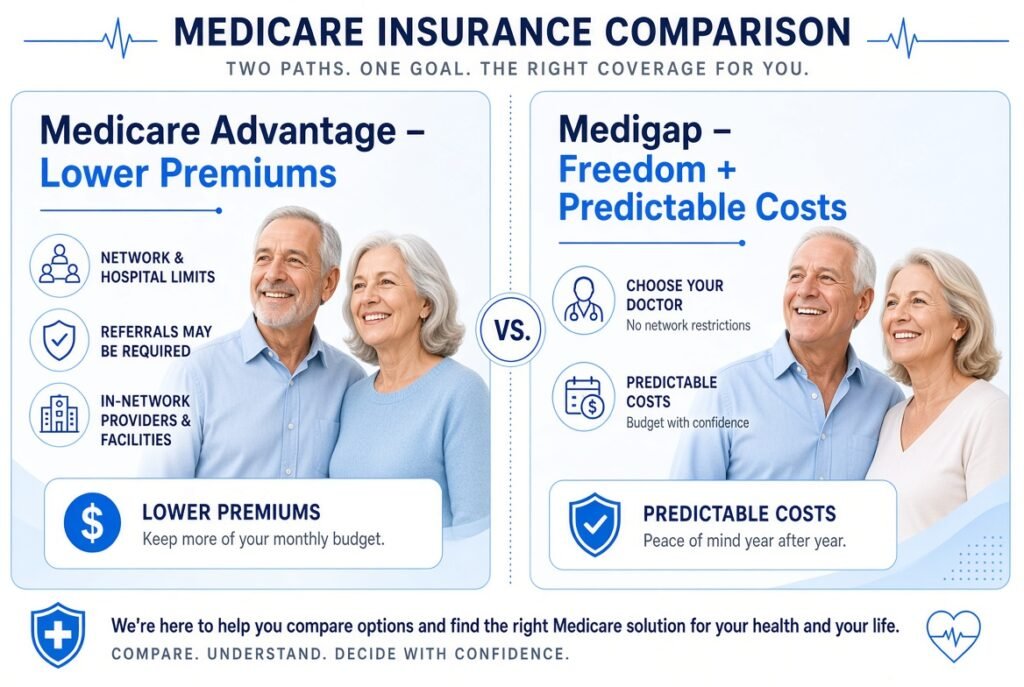
Medicare Advantage (Part C) is an all-in-one plan offered by private insurers. It usually includes Part D prescription coverage and often extras like dental, vision, hearing, and gym memberships. Monthly premiums can be as low as $0 (beyond your Part B premium). The trade-off? You typically must use doctors and hospitals in the plan’s network. Prior authorizations are more common, and if you travel a lot or want specialist freedom, it can feel restrictive.
Medigap policies work differently. You keep Original Medicare and add a standardized supplement (plans G, N, etc. are the most popular in 2026). Medigap pays most or all of the remaining costs after Medicare. You can see any doctor who accepts Medicare—no networks. The downside is higher monthly premiums and you’ll still need a separate Part D drug plan.
Which one wins?
- Choose Medicare Advantage if you want lower (or zero) premiums, like the extras, and you’re comfortable with a network.
- Choose Medigap if you value flexibility, predictable costs, and the ability to see any Medicare provider without referrals or prior auth headaches.
Important 2026 notes: Star ratings still matter for Advantage plans. Plan G remains the most comprehensive Medigap option for most new enrollees. And once you drop Medigap, getting back in later can be difficult or more expensive because of underwriting.
The best move is to list your doctors, preferred hospitals, expected prescriptions, and travel habits—then compare actual plan details side by side. Free tools from Medicare.gov or licensed independent agents make this much easier than guessing.
Your health and peace of mind are worth the extra 30 minutes of research.
Aur topics jo high CPM dete hain (agar zyada chahiye to bolo):
- “How much life insurance do I need calculator” style guides
- Best car insurance for [high-risk / seniors / new drivers]
- Home insurance claims tips after storms
- Annuity rates comparison 2026
- Business liability insurance for small LLCs